Financing Terms Every Aspiring Female Owner Should Know
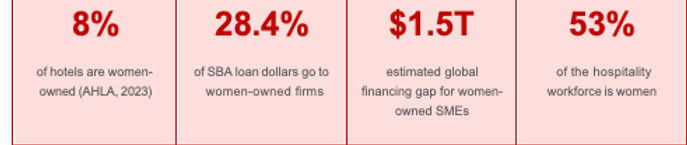
Women make up more than 50% of the hospitality workforce. Women run the front desk, manage the teams, build the culture, and keep the guests coming back. Yet according to a 2023 report by the American Hotel and Lodging Association (AHLA), women-owned businesses represent just 8% of the hotel industry. That gap isn’t about capability. It is, in large part, about access to capital, access to knowledge, and access to the vocabulary that makes the world of commercial finance feel navigable rather than foreign.
The data on gender and business lending is stark. According to SBA loan data for fiscal year 2023, women-owned businesses received just 28.4% of the total dollars approved across the 7(a) and 504 loan programs — despite women now owning 35% of U.S. employer firms. Pre-pandemic research showed that 85% of male business owners who applied for a small business loan were approved, compared to just 36% of women. Even when women do secure financing, studies show the amounts tend to be smaller and often require more collateral.
Goldman Sachs has estimated the global financing gap for women-owned small and medium enterprises at $1.5 trillion. Let that number sink in.
Part of what drives this disparity is structural and systemic — bias in lending practices, limited mentorship networks, and historical exclusion from the financial decision-making table. But part of it is also informational. The language of hotel finance — DSCR, cap rates, CMBS, key money — is not taught in most business programs, and it is rarely shared in spaces designed for women. This article aims to change that, at least in a small way. Consider it a primer: a plain-language translation of the terms you will encounter when exploring hotel ownership, so the vocabulary never stands between you and the deal.
Section 1: The Capital Stack
When you finance a hotel, you are rarely using one source of money. Most deals are funded through a “capital stack” — layers of financing, each with different risk profiles, returns, and repayment priority. Think of it like a building: the lowest floor bears the most weight and gets paid back first; the upper floors carry more risk but potentially higher reward.
Section 2: Loan Types
Understanding which financing vehicle fits your situation is one of the most important decisions you’ll make. Here are the most common options in the hotel space:
SBA 7(a) Loans
The Small Business Administration’s flagship loan program. Available up to $5 million, with flexible use of proceeds including working capital, acquisitions, and renovations. Backed by the federal government, which gives lenders more confidence to approve borrowers they might otherwise pass on. This is often one of the best entry points for first-time hotel owners.
Important note: Women-owned businesses have historically been underrepresented in SBA lending, but the program is intentionally designed to serve underserved borrowers. In fiscal year 2023, SBA 7(a) volume to women-owned businesses topped $5 billion — a 69% increase from 2020. The trend is moving in the right direction.
SBA 504 Loans
Designed specifically for major fixed assets — real estate and equipment. Can be used to purchase or renovate a hotel property. Maximum of $5.5 million at fixed interest rates, structured in partnership with a Certified Development Company (CDC) and a private lender. Typically requires a 10% down payment, lower than conventional commercial loans.
Conventional Commercial Loans
Standard bank loans for commercial real estate. Typically require 20–30% down, stronger credit history, and demonstrated cash flow. Terms vary widely by lender. Community banks and regional lenders are often more flexible than large national banks — especially for first-time buyers.
Bridge Loans
Short-term financing used to “bridge” a gap — for example, while you renovate a property before securing long-term financing. Higher interest rates, shorter terms. A tool, not a long-term solution.
CMBS — Commercial Mortgage-Backed Securities
A pool of commercial real estate loans are packaged and sold to investors as securities. CMBS loans often offer competitive rates but come with stricter terms and limited flexibility for modifications. Common in larger hotel transactions. If you’re evaluating a property financed with CMBS debt, know that these loans are often non-recourse (protecting your personal assets) but can be rigid if you need to make changes mid-term.
Section 3: Key Metrics Lenders Care About
Before a lender says YES, they will run the numbers. These are the metrics that show up in every conversation, every underwriting package, every term sheet. Know them well.
Section 4: Franchise-Specific Financing Considerations
Acquiring a branded hotel — including economy brands that are accessible to first-time owners — comes with franchise-specific financial considerations that pure commercial lenders may not initially flag. Here are a few concepts to understand:
Section 5: Questions to Ask Before You Sign
No lender, broker or franchisor expects you to know everything. But the questions you ask signal how prepared and serious you are. Here are questions worth having in your toolkit:
Questions for Lenders:
-
What is the minimum DSCR you require for this loan type, and how do you calculate it?
-
What LTV are you comfortable with for an economy or limited-service hotel?
-
Do you have experience lending to women-owned businesses or first-time hotel operators?
-
Are there prepayment penalties, and how do they work?
-
What does the underwriting process look like, and what documents will you need from me?
-
Do you offer SBA programs, and is this deal a candidate for one?
Questions for Your Advisors:
-
What is a reasonable cap rate range for this market and hotel type right now?
-
Have you reviewed the franchise agreement and PIP requirements?
-
What is your projection for NOI in years one through three?
-
What am I missing?
Who Should Be on Your Team
Hotel ownership is a team sport. Before you get to closing, you want:
-
A commercial real estate attorney experienced in hotel transactions and franchise agreements.
-
A CPA who understands hospitality financials, depreciation strategy, and entity structure.
-
A commercial real estate broker who specializes in hotels — not general commercial properties.
-
A lender relationship, ideally with a community bank, regional lender, or SBA-preferred lender with hotel experience.
Closing: The Door Is Open
The financing world was not built with women in mind. The language, the networks, the rooms where deals are made — they all have a historical legacy that is only now beginning to shift. But shift it is.
Women-owned businesses are growing at nearly double the rate of male-owned businesses. Women of color are among the fastest-growing entrepreneur segments in the country. And the hotel industry — one built on hospitality, connection, and service — is one where women have always been central, even if the ownership structures didn’t reflect it.
The gap is not a reflection of your capability. It is a reflection of access. And access begins with knowledge.
Know the terms. Ask the questions. Build the team. The room is yours.
Resources Worth Exploring
SBA Women's Business Centers (WBCs) — Free counseling and financing guidance for women entrepreneurs. sba.gov/local-assistance/resource-partners/womens-business-centers
NAWBO — National Association of Women Business Owners. nawbo.org
AHLA Women in Lodging — Industry group supporting women in hotel leadership and ownership. SCORE — Free mentoring for small business owners, including hospitality. score.org
Bridge Capital – bridgecapitalmanagement.com
Visit https://www.redrooffranchising.com/ride for more information about the RIDE with Red Roof program, which aims to diversify and expand hotel ownership opportunities to women and underrepresented groups by providing access to the network, educational resources, capital and industry vendor partners.